


Dad Needs to Move. But the Money Is Still in the House.
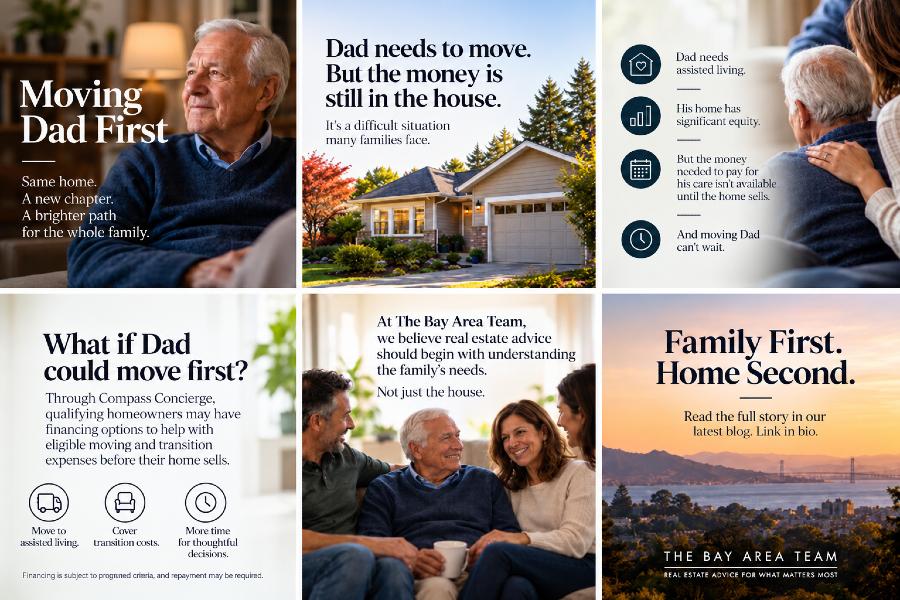
The family knew Dad needed to move.
Perhaps it was a health or safety concerns. Perhaps the cost of caring for him at home had become overwhelming. Or perhaps everyone had reached the difficult realization that living independently was no longer the best option.
But knowing Dad needed to move was only the beginning. The family faced another challenge: Dad had substantial equity in his home, but the money needed for his next chapter of care was locked inside it.
The assisted living community required funds before he could move in. There were moving expenses, years of belongings to sort through, and a home that needed to be prepared for sale.
The family needed to sell the home to fund Dad's care. But they needed money to move Dad before they could sell the house. And suddenly, an already emotional family decision became a financial dilemma.
What if the parent could move first, and the home could be sold afterward?
A Financial Bridge Families May Not Know Exists
At The Bay Area Team, we believe that caring for a parent should come before worrying about the logistics of selling their home.
But what if the family didn't have to choose between paying for Mom or Dad's next chapter of care and preparing their home for sale?
That's where Compass Concierge may be able to help.
While traditionally it is used to help homeowners prepare their properties for sale, Compass Concierge can also help qualifying families cover moving expenses and approved senior care facility costs.
For families with substantial home equity but limited available cash, this can create valuable breathing room.
Mom or Dad may be able to settle into their new living environment while the family takes the time to sort through belongings, prepare the property, and make thoughtful decisions about selling, without having to rush the process or personally advance all the expenses.
How Does the Financing Work?
Through Compass Concierge, eligible homeowners may qualify for financing equal to 10% of their home's listing price, up to a maximum of $75,000.
For example, a home listed at $1 million could qualify for the full $75,000, subject to credit approval and program requirements.
Interest applies to the borrowed funds, and repayment is required when the home sells or within 12 months, whichever occurs first. Other repayment triggers may apply under the loan agreement.
More Time to Make Thoughtful Decisions
Moving a parent into a safe, comfortable living environment before selling the family home can make an enormous difference.
Mom or Dad can settle into their new surroundings while the family addresses their home without the daily disruption of contractors, repairs, and showings.
The children can thoughtfully sort through belongings, make decisions about necessary improvements, and prepare the home for sale.
And rather than making hurried decisions under financial pressure, the family can develop a plan designed to protect both their parents’ well-being and the value of their real estate.
Not every home needs extensive improvements. Sometimes a thoughtful cleanout and careful preparation are all that's necessary. Our responsibility is to help families understand which expenses make sense and which may not.
Keeping the Family on the Same Page
When several siblings are involved, financial decisions can become complicated.
One child may be able to contribute toward their parent's care while another cannot. Differences in opinions, resources, and responsibilities can create unexpected family tensions.
We encourage families to discuss the available options early, establish a clear budget, and designate one family member as the primary contact for coordinating the home's preparation and sale.
All proposed work should be documented and approved by the individuals with the appropriate legal authority before expenses are incurred.
A clear plan, shared understanding, and open communication can make a difficult transition easier for everyone.
An Important Resource for Trusted Advisors
Estate and trust attorneys, financial advisors, senior living community operators, and care professionals often help families navigate these decisions.
Understanding that financing may be available before the family home sells gives these professionals another option to discuss with the people they serve.
The best outcomes often come when the family's trusted advisors work together, each contributing their expertise while keeping the parent's needs at the center of the conversation.
Family First. Home Second.
A family home represents much more than real estate. It holds memories, financial security, and often a lifetime of hard work.
At The Bay Area Team, we understand that selling a parent's home is rarely just a real estate transaction. It's an important family transition that deserves thoughtful planning, sound advice, and compassion.
Compass Concierge won't be the right solution for every family. But knowing the option exists may help families make decisions they didn't realize were possible.
Because the most important question isn't how quickly we can sell the parent's home. It's how thoughtfully we can help the parents begin their next chapter.
That's what we mean by Family First. Home Second.
And that's the kind of real estate advice we believe every family deserves.
Important Financing Information
Up to 10% of the home's list price is allowed for the loan, capped at a maximum of $75,000. The loan amount may vary depending on FICO score and other factors. A minimum FICO score of 680 is required for loans up to $50,000, and a minimum FICO score of 780 is required for loans over $50,000. The homeowner must have approximately 20% equity in the home.
Interest applies. Loan funds, interest, and fees are due upon closing of the sale of the homeowner's home, termination or expiration of the homeowner's listing agreement, suspension of the loan, loan acceleration, or twelve months after loan origination, whichever occurs first.
Notwithstanding the Loan Repayment Date in the loan agreement, an origination fee will apply, and interest will continue to accrue until the loan is repaid in full. Subject to the terms of the homeowner's loan agreement, as well as Notable's terms and conditions: Notablehome.com/terms.